Overnight money has caught up with the repo and October CPI was 6.09%. Our call: replace short paper that rolls in the next two quarters before the MPC meets on 2 to 4 December, and hedge payables in tranches.
The decision this week
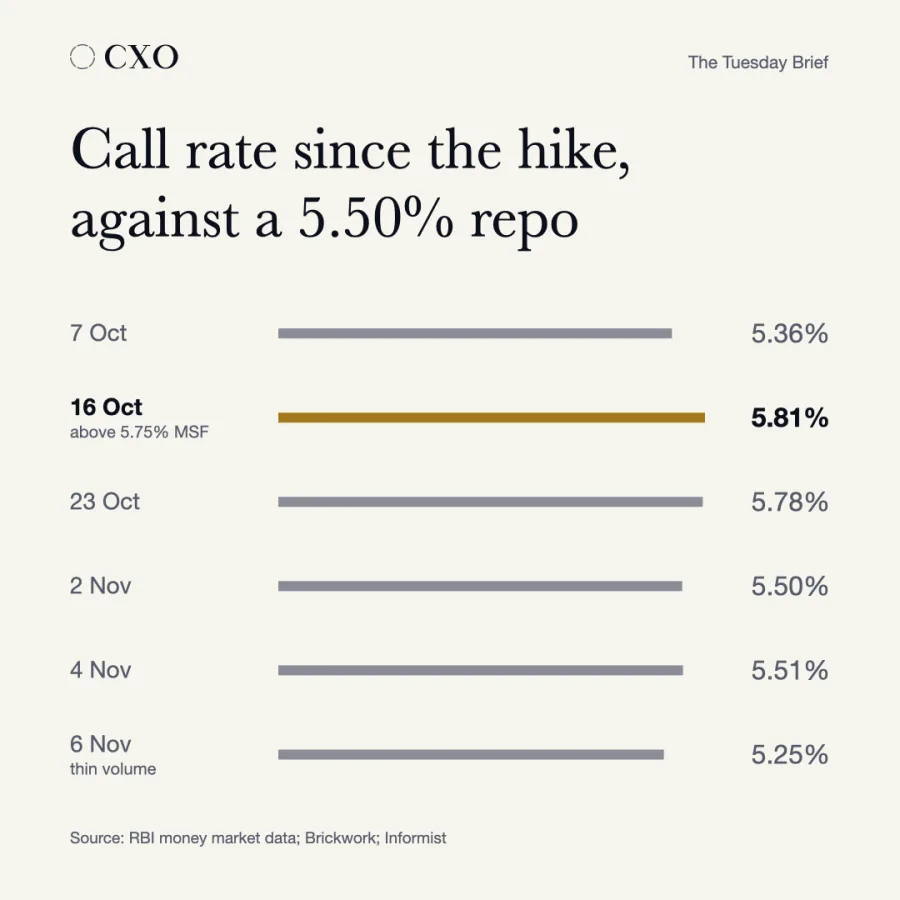
On 7 October, the day the MPC raised the repo by 25 basis points to 5.50%, the call rate was 5.36%, below it, and Brickwork Ratings counted a core liquidity surplus near ₹10 trillion. By 16 October the call rate was 5.81%, above the 5.75% marginal standing facility rate, and on 23 October it was 5.78%. Since then it has stayed close to the repo: 5.50% on 2 November, 5.59% on 9 and 11 November, and 5.45% on 12 November, the latest day the RBI has published.
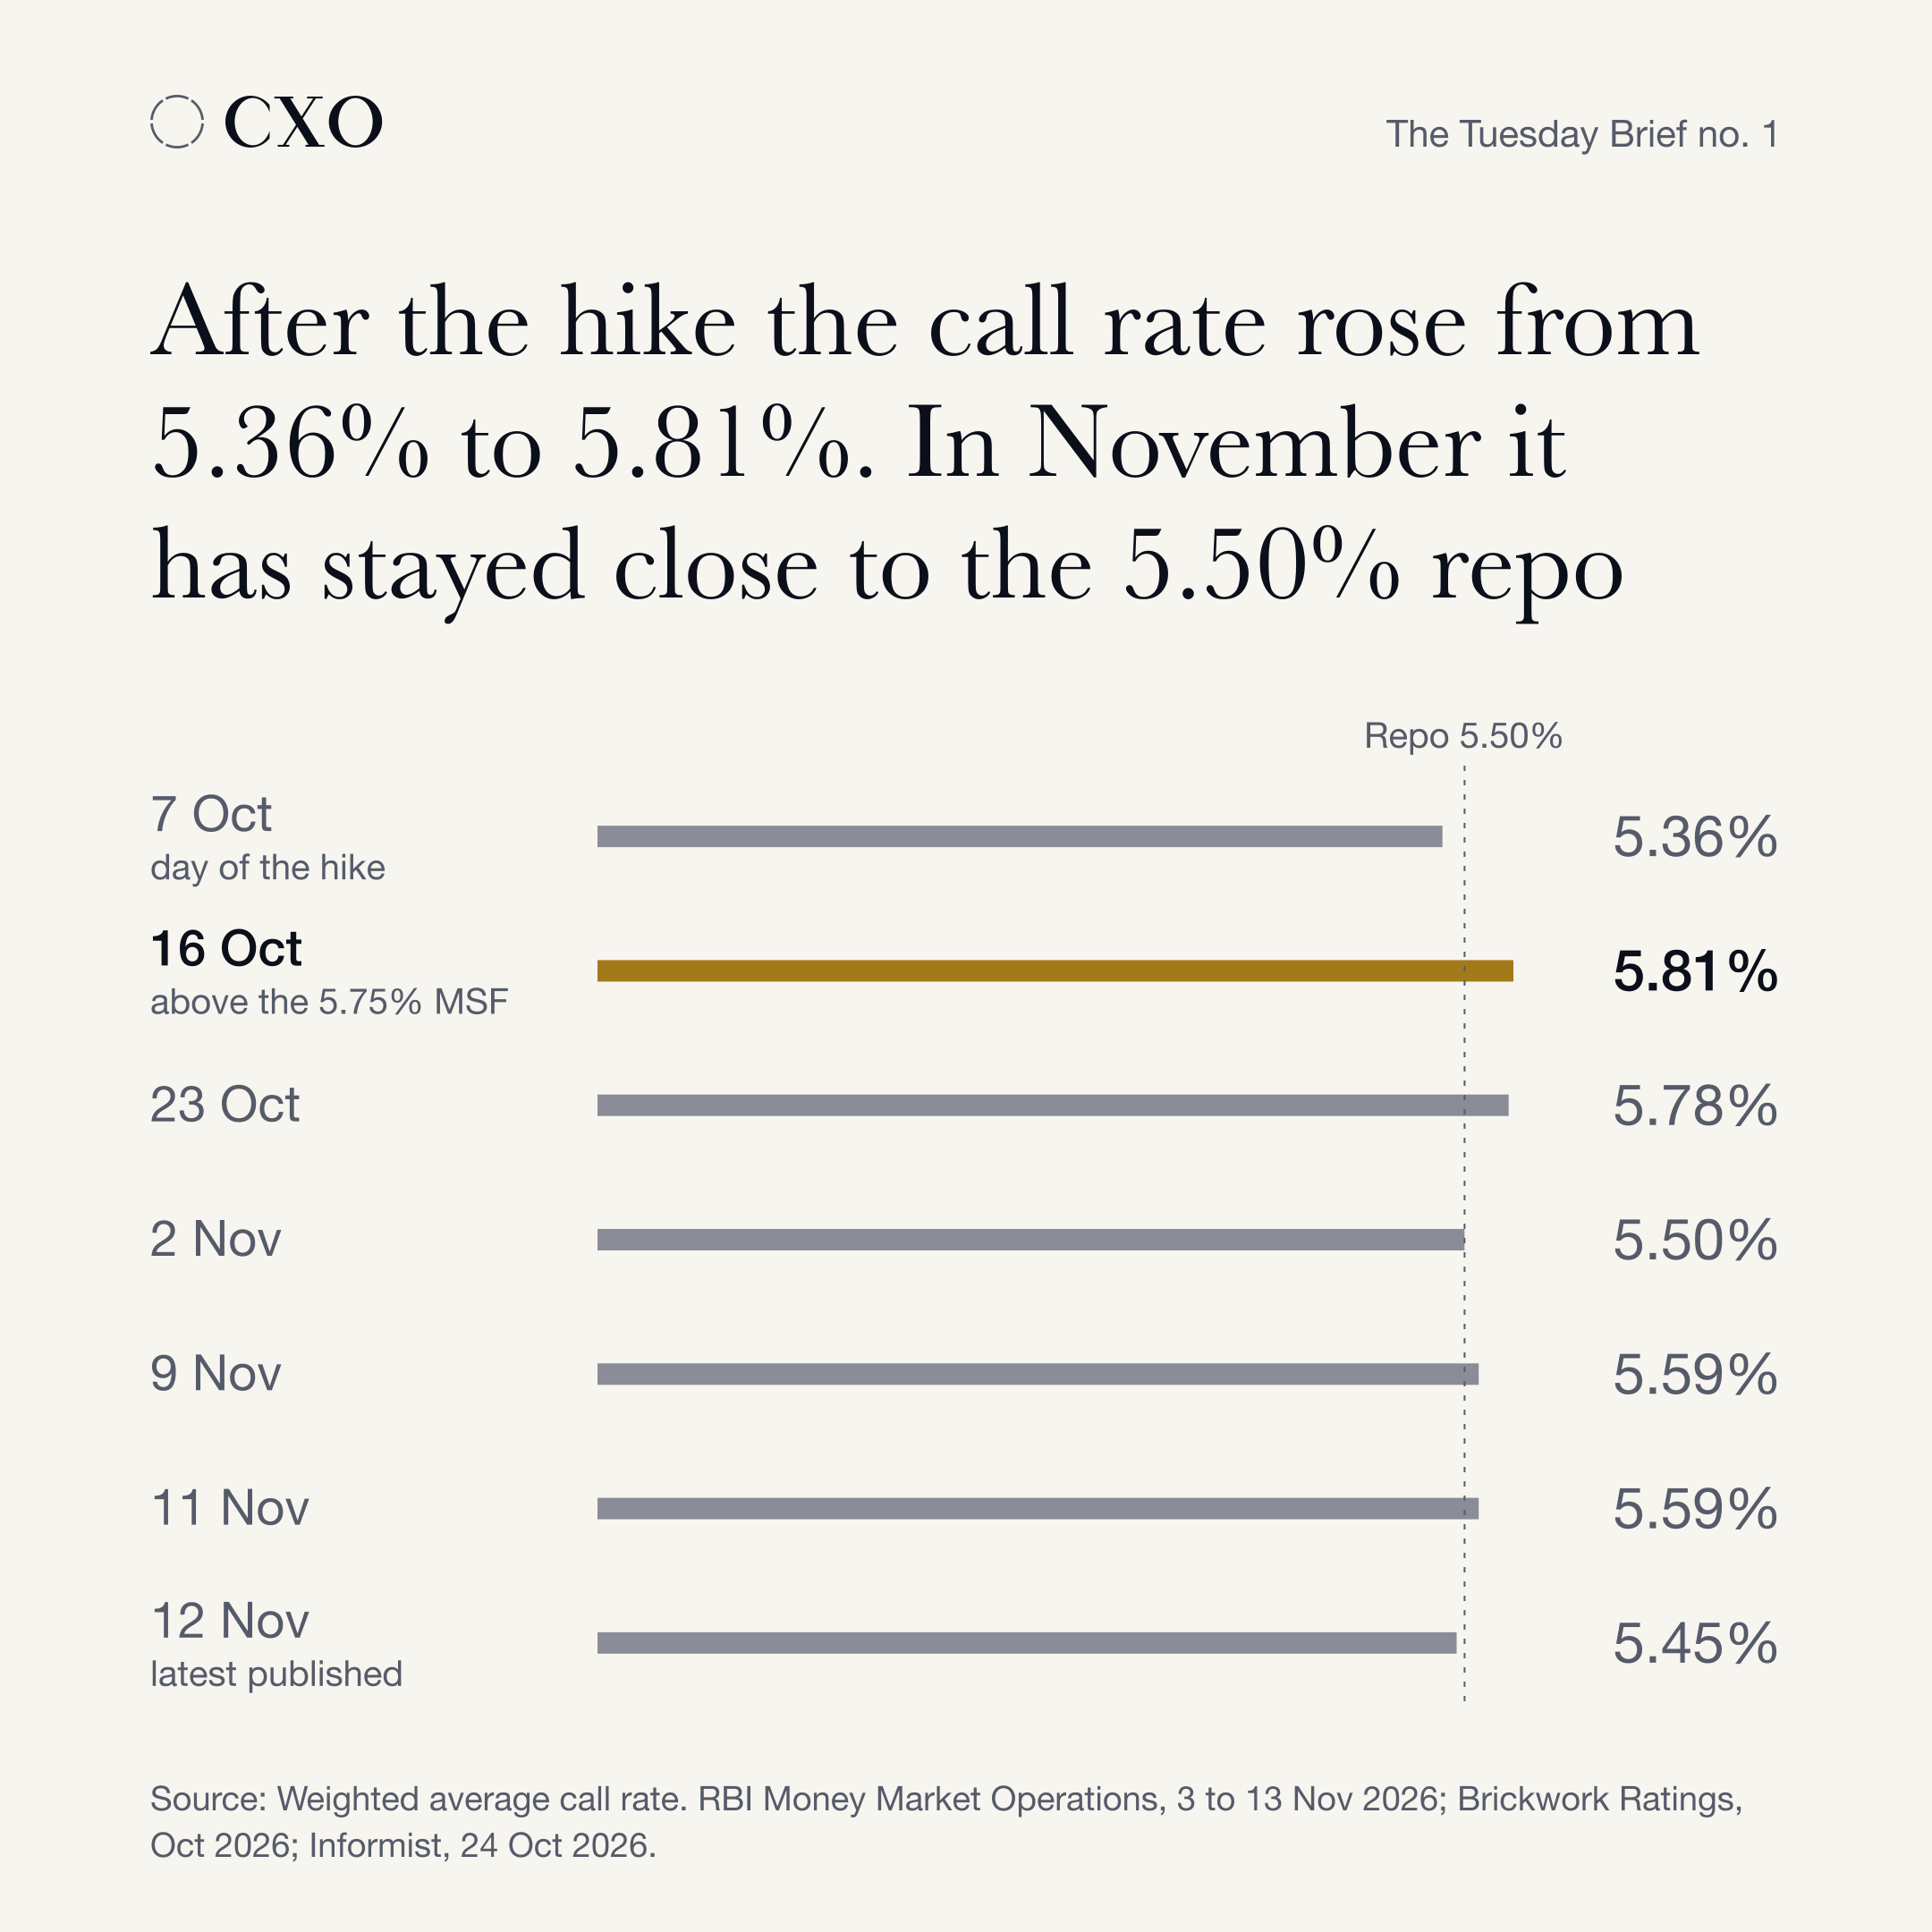
We read that swing as the surplus shrinking. It had reached a record ₹11.16 lakh crore on FCNR(B) inflows. Net absorption by the RBI, counting its outstanding operations, was ₹2.03 lakh crore on 6 November and ₹1.18 lakh crore on 12 November. A Bank of Baroda economist told Informist the RBI wants a surplus of about ₹2.50 to 3.00 lakh crore, so the system is now well under that. The figures come from different measures, so take them as direction only.
The RBI is now steering in both directions. On 9 November it put ₹50,003 crore back through a four-day repo auction at a weighted average of 5.54%. On 12 November it took ₹50,012 crore out overnight at 5.47%. On 13 November it offered to absorb ₹75,000 crore for three days and banks parked only ₹38,592 crore, a sign they have less spare cash than a month ago.
The wider overnight market has not caught up. Across call money, triparty repo and market repo, the overnight segment averaged 5.39% on 11 November and 5.36% on 12 November, below the repo. Short paper is still priced off that cheaper money, and we expect the gap to close.
Our position is to term out now, before the MPC meets on 2 to 4 December. Treasurers of heavily indebted mid-sized companies and market-funded NBFCs should replace short paper that rolls in the next two quarters. October CPI, released on 12 November, was 6.09%, up from 5.54% in September and above both the RBI's 6% upper tolerance limit and its own third-quarter projection of 6.0%. Food inflation rose to 8.94% from 7.74%. IDFC First Bank expects the RBI to raise the repo by 25 basis points in December and again in February.
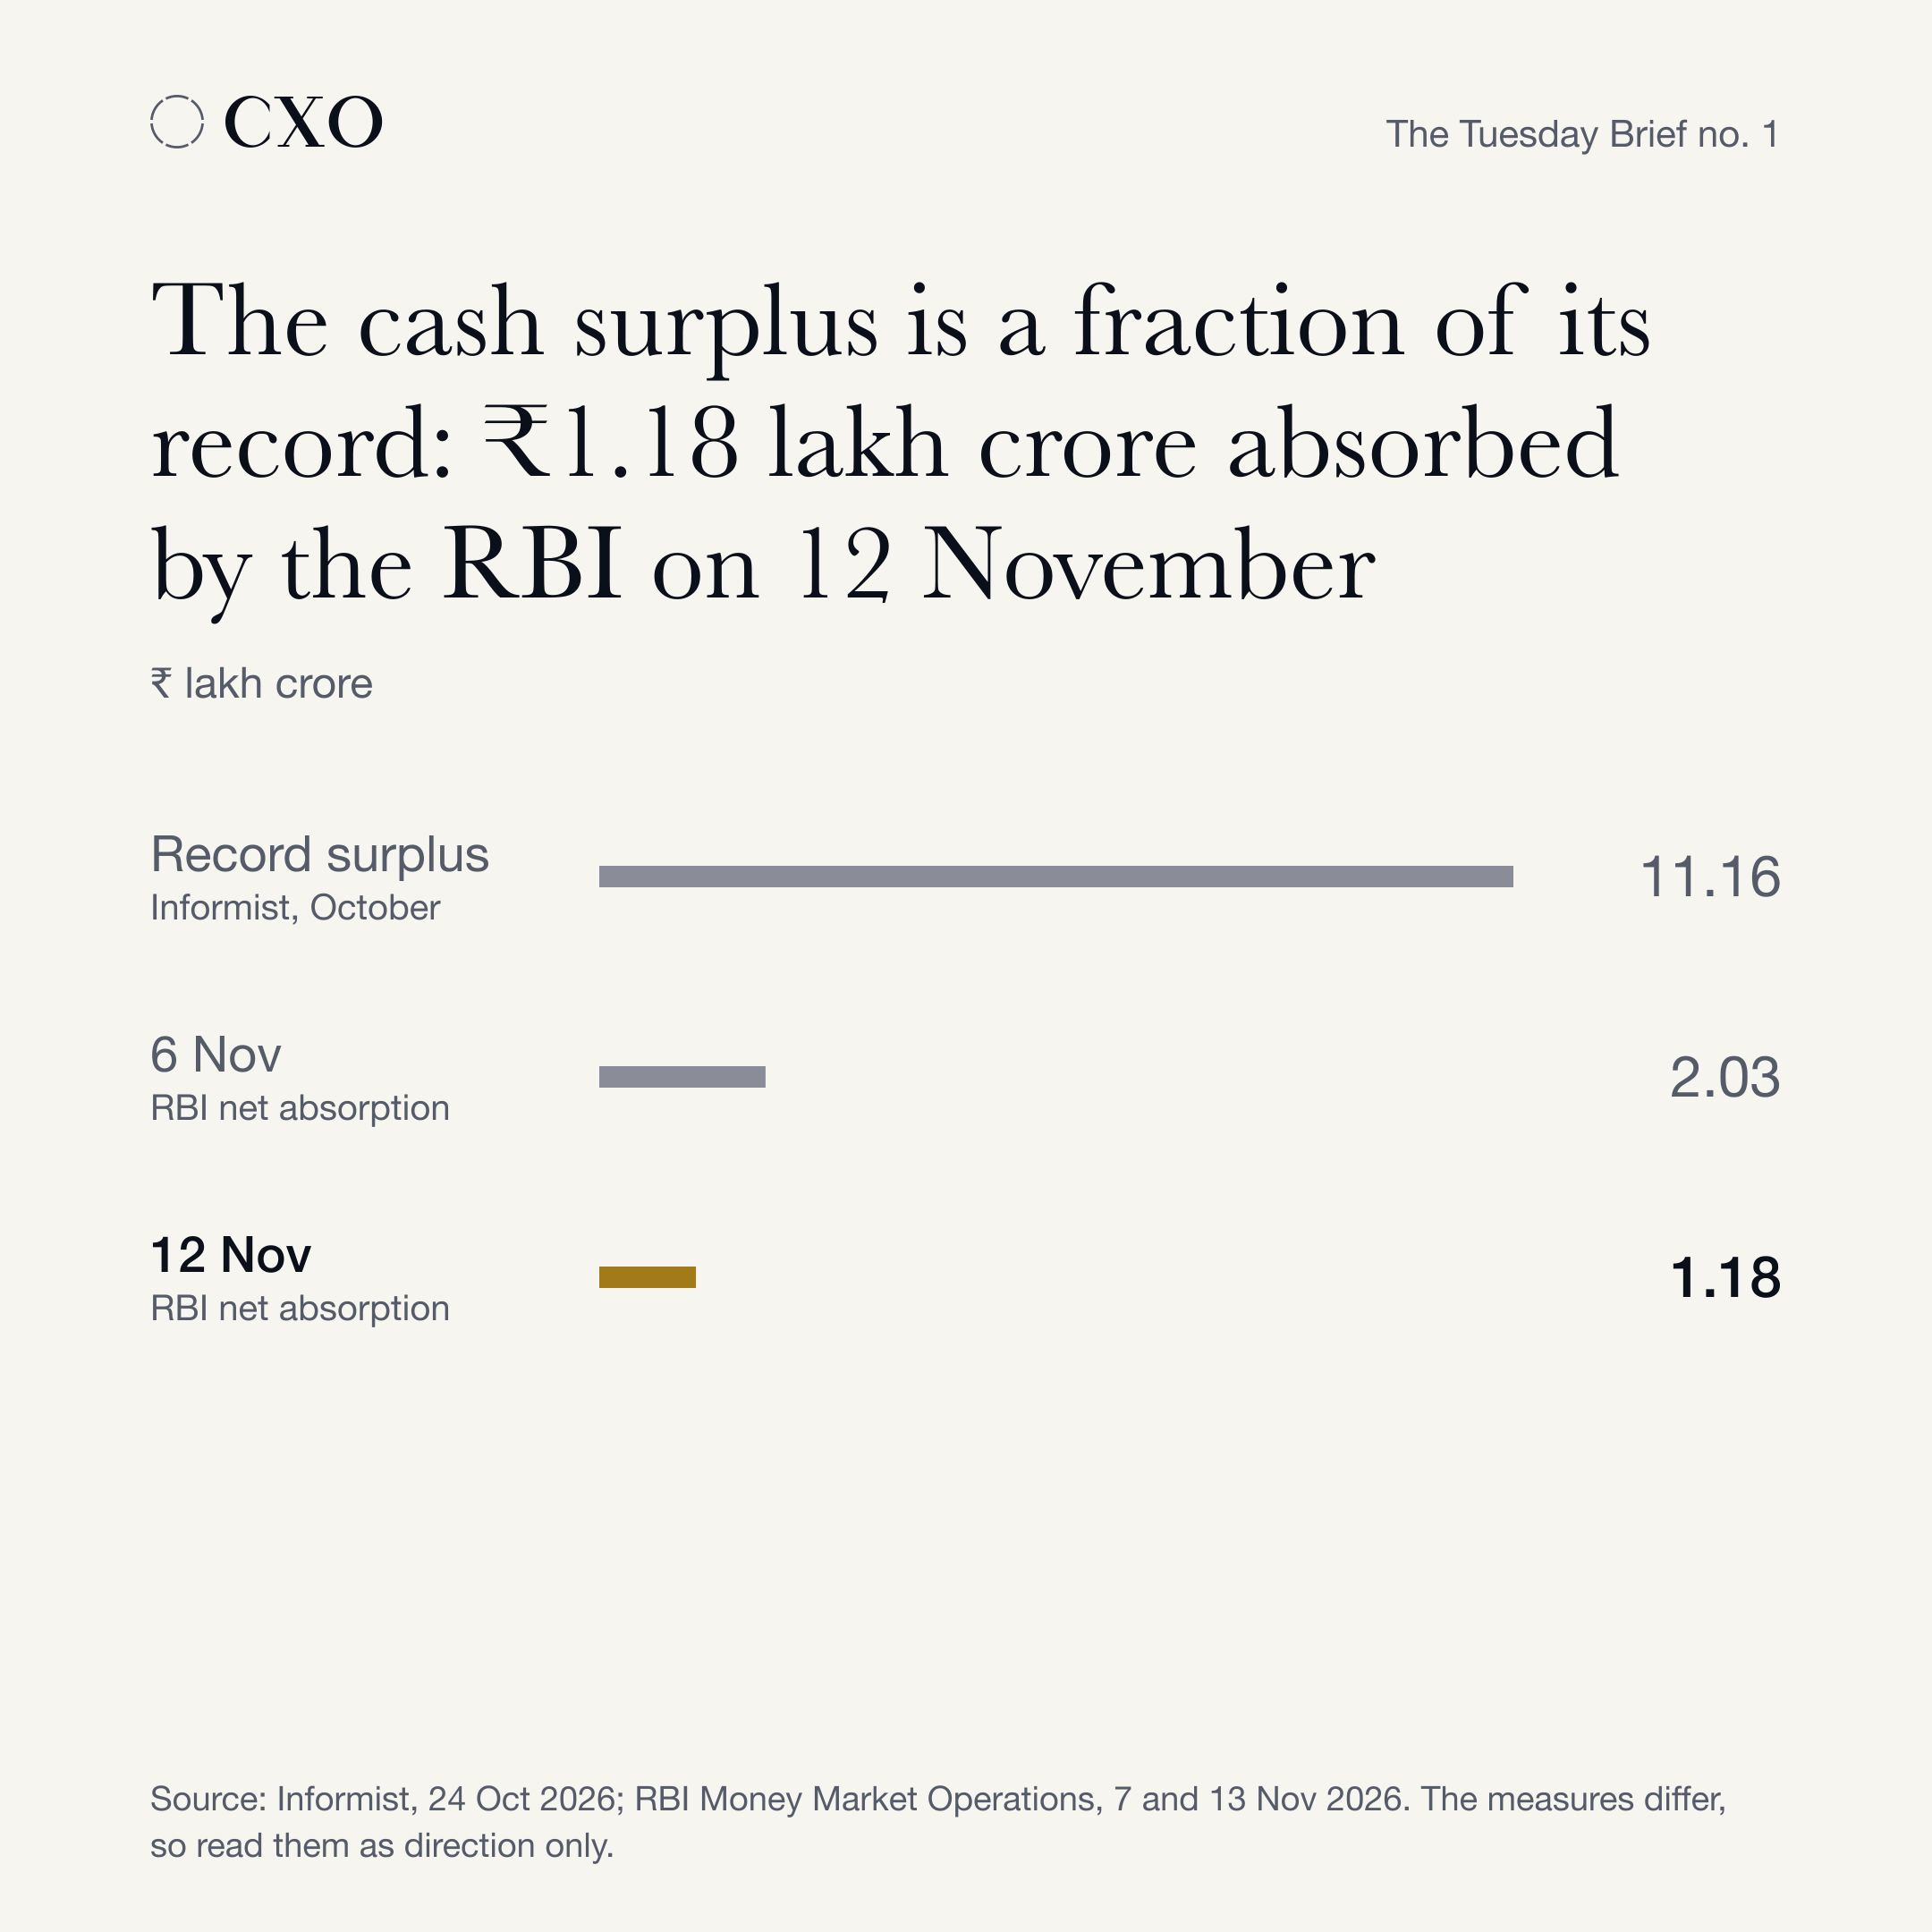
Long money has started to move. The 10-year government yield closed at 7.31% on 13 November, up 12 basis points in the week and above the 7.27% of 7 October. Treasury bills cleared at 5.87% for 91 days and 6.64% for 364 days on 11 November. A mid-sized borrower will pay more than these benchmarks: the latest AAA corporate yield we could date was 7.88%, in early November. We would still pay the gap over the repo for certainty while inflation sits above the band.
Hedging is a separate decision, and the rules changed on 10 October. Banks must now hold 20% of notional as cash with the RBI on client contracts above $2 million that hedge current account payments by buying foreign currency against rupees. Reuters reported the cost reaching clients at about 11 to 14 paisa a month. The limit for hedging without proving an exposure fell from $100 million to $5 million, and a cancelled contract cannot be rebooked. Rollovers are still allowed, but the RBI's FAQs of 15 October treat a rolled-over contract as a fresh one, so the reserve and its cost apply again at every roll.
The rupee closed at 94.19 on 13 November. It had weakened to 96.78 after the hike and recovered to 93.77 by 9 November. IDFC First Bank expects 92 to 94 by December, 94 to 95 by March 2027 and 96 by June 2027, which makes this a reasonable level to add cover on payables due inside twelve months. Book only the cover you intend to hold, in tranches matched to the payable dates, so short rolls do not pay the reserve again. Write two triggers down today. If the call rate holds above the 5.75% ceiling, finish terming out. If the rupee goes back through 96, complete the cover.
Abroad
Bank Indonesia faced the same pressure in October and went the other way on hedging. On 21 October it held its rate at 5.75%, lifted the deposit facility rate to 5.00%, and raised DNDF hedge premium reductions from 25% to 40% at 6 months and from 30% to 45% at 12 months. The RBI charges the dollar buyer; Indonesia pays the hedger. Bank Indonesia credits its policies with drawing USD 9.9 billion of foreign capital between June and 20 October. Its next decision is due on 18 November, the day after this issue.
The rupee has done better so far. The rupiah closed at Rp17,985 on 20 October, the JISDOR reference rate was Rp18,218 on 13 November, and MUFG expects 18,350 by end-2026. A month is too short a test of either policy, and the rupee has had help from RBI dollar sales. India and the Philippines were the only two to raise rates in October, in a Reuters sample of 18 emerging economies.
Five moves that matter
Mohit Malhotra, Dabur India. He left as Global CEO and whole-time director on 13 November, after 32 years, for an undisclosed role overseas. No Global CEO successor is named. India CEO Herjit Singh Bhalla was due to join the board on 14 November and P D Narang keeps international, so India and overseas now run on separate lines. (source)
P N Vasudevan, Equitas Small Finance Bank. He resigned as MD and CEO on 29 October, citing investor concerns over a perceived conflict of interest linked to his daughter's role as co-promoter of a housing finance company, and the shares fell 20% intraday. Whole-time director Balaji Nuthalapadi was named interim MD and CEO on 3 November, subject to RBI approval, and Mr Vasudevan was relieved on 6 November. The interim term of up to three months gives the board's search an early-February deadline. (source)
Dr Amrut Naik, Alkem Laboratories. He became CEO on 11 November, after leaving his post as President, International Markets, at Zydus Lifesciences on 7 November. He replaces Dr Vikas Gupta, and the hire points to overseas growth as the brief. (source)
Pratap Singh, Fino Payments Bank. The RBI approved him as MD and CEO for three years in a letter dated 12 November, and he is due to take charge by 27 November. He headed retail and SME banking for the UK and Europe at ICICI Bank UK. He replaces an interim arrangement under CFO Ketan Merchant, put in place after the former MD and CEO, Rishi Gupta, was arrested in an alleged GST case. Shareholders still have to approve the appointment. (source)
Akshit Choudhary, Indian Overseas Bank. He moved from general manager to CFO on 1 November, on board approval of 27 October, replacing Madhaw Chandra Jha. A 40-year-old chartered accountant with a treasury diploma now has expected credit loss provisioning, which starts on 1 April 2027, on his desk. (source)
By the numbers
$719.55 billion in foreign exchange reserves for the week ended 6 November, up $2.49 billion almost entirely on the value of gold, and down from $785.71 billion on 4 September. Source, RBI and The Quint.
$239 billion is the RBI's net short forward dollar position as of September, with $40 billion maturing within a year. Source, IDFC First Bank via PTI.
₹5,736.55 crore of equities bought by foreign institutions, in exchange data PTI reported on 13 November, with Brent futures near $95.5 that day. Source, ThePrint (PTI).
Research note. This issue reports on regulatory texts, drafts and public filings as we read them on 14 November 2026. It is general information and is not legal, tax or investment advice. Drafts can change before they are final. Check the source documents and take your own professional advice before acting.
Sources
- MPC raised the repo rate by 25 basis points to 5.50% on 7 October 2026; SDF 5.25%, MSF 5.75%; stance calibrated tightening; Q3 CPI projection 6.0%; next meeting 2 to 4 December 2026 (re-checked 14 November). RBI, Resolution of the Monetary Policy Committee, 2026-10-07.
- Weighted average call rate 5.36% on 7 October; core surplus about ₹10 trillion; rupee weakened to 96.78 per dollar after the hike; 10-year yield 7.27% on 7 October. Brickwork Ratings, RBI MPC Meet Outcome, October 2026, 2026-10.
- WACR 5.81% on 16 October and 5.78% on 23 October; record surplus ₹11.16 lakh crore from FCNR(B) inflows; Bank of Baroda's Madan Sabnavis: RBI wants a surplus up to 1% of NDTL, about ₹2.50 to 3.00 lakh crore. Informist Media, TREND: RBI actions suggest comfort with WACR above repo, 2026-10-24.
- Money Market Operations, 2 November: call money 5.50%. RBI press release, 2026-11-03.
- Money Market Operations, 6 November: net liquidity absorbed, outstanding included, ₹2,03,423.13 crore. RBI press release, 2026-11-07.
- Money Market Operations, 9 November: call money ₹14,551.04 crore at 5.59%. RBI press release, 2026-11-10.
- Money Market Operations, 11 November: call money ₹15,202.33 crore at 5.59%; overnight segment 5.39%. RBI press release, 2026-11-12.
- Money Market Operations, 12 November: call money ₹16,530.81 crore at 5.45%; overnight segment 5.36%; net absorption, outstanding included, ₹1,17,787.13 crore. RBI press release, 2026-11-13.
- Four-day VRR auction on 9 November: allotted ₹50,003 crore, cut-off 5.51%, weighted average 5.54%. RBI, Result of the 4-day VRR auction, 2026-11-09.
- Overnight VRRR auction on 12 November: notified ₹50,000 crore, accepted ₹50,012 crore, weighted average 5.47%. RBI, Result of the Overnight VRRR auction, 2026-11-12.
- Three-day VRRR auction on 13 November: notified ₹75,000 crore, offers ₹38,592 crore, all accepted at 5.49%. RBI, Result of the 3-day VRRR auction, 2026-11-13.
- October 2026 CPI inflation 6.09% (provisional), food (CFPI) 8.94%, against 5.54% and 7.74% in September. DD News, on the MoSPI release, 2026-11-12. MoSPI release: https://www.mospi.gov.in/uploads/latestReleases/latest_release_1794478693814_7c90e80f-9e64-4aa4-b44a-1dc727b0fed9_Press_Release_of_CPI_for_October_2026_.pdf
- IDFC First Bank expects the rupee at 92 to 94 by December 2026, 94 to 95 by March 2027 and 96 by June 2027, and 25 basis point hikes in December and February; RBI net short forward position USD 239 billion as of September, USD 40 billion maturing within a year. The Week (PTI), 2026-11-09.
- India 10-year yield closed at 7.3079% on 13 November, up 12 basis points on the week. Rallies.ai (Reuters bond wrap), India 10-year bond yield reverses half of last week's drop on elevated inflation, 2026-11-13.
- Treasury bill auction of 11 November: 91-day cut-off yield 5.8681%, 364-day 6.6394%. RBI, T-bill auction result, 2026-11-11.
- AAA corporate yield 7.88% (week before 9 November; tenor not stated). Alpha Alternatives, An early Diwali for Indian Bonds, 2026-11-09.
- Foreign Exchange Risk Reserve of 20% of notional, held as cash with RBI, for user contracts above USD 2 million where the user buys foreign currency against INR. RBI A.P. (DIR Series) Circular No. 26, 2026-10-10.
- Hedging without established exposure cut from USD 100 million to USD 5 million; cancelled contracts may not be rebooked; rollovers at maturity permitted. RBI A.P. (DIR Series) Circular No. 25, 2026-10-10.
- RBI FAQs on the Foreign Exchange Risk Reserve: a rolled-over contract is treated as a fresh contract and attracts the reserve (Q18). RBI FAQs, 2026-10-15.
- Clients pay about 11 to 14 paisa more per month to lock in future dollar purchases. Reuters via Investing.com, India importers press on with rupee hedges, 2026-10-14.
- Rupee closed at 94.19 on 13 November; foreign institutions bought ₹5,736.55 crore of equities; Brent futures $95.47 (intraday). ThePrint (PTI), Rupee falls 7 paise to close at 94.19, 2026-11-13.
- Rupee closed at 93.77 on 9 November. Deccan Chronicle, 2026-11-09.
- Foreign exchange reserves USD 719.547 billion in the week ended 6 November, up USD 2.490 billion, gold USD 104.796 billion (up 2.205). RBI, Weekly Statistical Supplement extract, 2026-11-13.
- Forex reserves peaked at USD 785.71 billion on 4 September 2026. The Quint, opinion by Subhash Chandra Garg, 2026-10-21.
- Bank Indonesia held the BI-Rate at 5.75% on 21 October, raised the deposit facility rate to 5.00%, raised DNDF premium reductions from 25% to 40% (6 months) and 30% to 45% (12 months); USD 9.9 billion of foreign capital inflows since June, as of 20 October; rupiah Rp17,985 on 20 October. Bank Indonesia, BI-Rate Held at 5.75%, 2026-10-21.
- Bank Indonesia Board of Governors meeting schedule for 2026: 17 to 18 November. Bank Indonesia, 2025-12-22.
- JISDOR Rp18,218 on 13 November 2026. Bank Indonesia, JISDOR, 2026-11-13.
- MUFG forecasts USD/IDR at 18,350 by end-2026. FXStreet, citing MUFG, 2026-10-22.
- In a sample of 18 emerging economies, India and the Philippines raised rates in October. Reuters via Investing.com, 2026-11-04.
- Equitas SFB: P N Vasudevan resigned on 29 October citing investor concerns over a perceived conflict of interest; shares fell 20% intraday; interim MD and CEO named 3 November subject to RBI approval. Free Press Journal, 2026-10-30. Relief on 6 November: Multibagg, 2026-11-06.
- Alkem: Dr Vikas Gupta resigned as CEO. Multibagg summary of Alkem filing, 2026-11-05.
- Expected credit loss provisioning takes effect on 1 April 2027. RBI press release 2026-2027/150, 2026-04-27.